Loan-to-Value Ratio: Why Banks Do Not Finance the Entire Asset Value
When someone purchases a house, car or another asset using a loan, it may seem reasonable to expect the lender to finance the entire purchase price.
However, lenders usually do not provide 100% financing.
One important reason is the Loan-to-Value (LTV) ratio.
LTV helps a lender compare the amount being borrowed with the value of the asset being used as security. It is an important concept in secured lending because it helps manage the lender’s exposure if the borrower cannot repay the loan.
What Is Loan-to-Value Ratio?
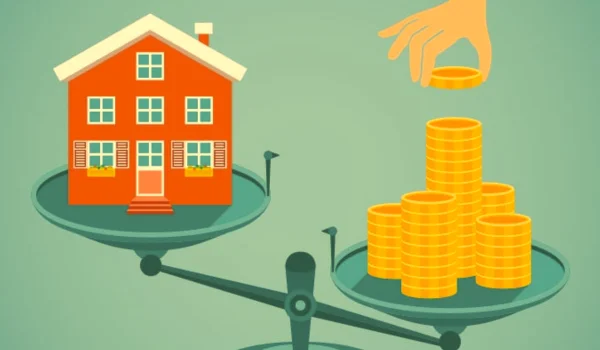
The Loan-to-Value ratio compares the loan amount with the value of the underlying asset.
A commonly used formula is:
LTV Ratio = Loan Amount ÷ Asset Value × 100
For example, suppose a property is valued at ₹50 lakh and the lender provides a ₹40 lakh loan.
The LTV would be:
₹40 lakh ÷ ₹50 lakh × 100 = 80%
This means the loan represents 80% of the asset’s value.
The remaining 20% represents the portion that is not financed through the loan.
Why Banks Do Not Usually Finance 100%
The main reason is risk protection.
Suppose a bank finances the entire ₹50 lakh value of a property.
If the borrower later defaults and the lender has to recover its money by selling the property, the property may not necessarily sell for ₹50 lakh.
The actual recovery value can be affected by:
- Market conditions
- Property condition
- Time required to sell
- Legal issues
- Transaction costs
- Changes in property prices
If the property sells for less than the outstanding loan, the lender could face a loss.
A lower LTV gives the lender a greater cushion against such situations.
A Simple Example
Imagine a property is worth ₹60 lakh.
A lender provides a loan of ₹45 lakh.
The LTV is:
₹45 lakh ÷ ₹60 lakh × 100 = 75%
The borrower contributes the remaining ₹15 lakh, excluding applicable transaction costs and other expenses.
Now suppose the property’s value falls to ₹50 lakh.
The lender’s original loan is still ₹45 lakh, assuming no principal has been repaid.
The loan therefore represents:
₹45 lakh ÷ ₹50 lakh × 100 = 90%
The lender’s safety margin has become much smaller.
This illustrates why lenders consider LTV when deciding how much to finance.
LTV Creates a Borrower’s Equity Cushion
The portion of the asset not financed through the loan represents the borrower’s own contribution.
For example:
Asset value: ₹50 lakh
Loan: ₹40 lakh
Borrower’s contribution: ₹10 lakh
The borrower therefore has a 20% initial equity contribution.
This can provide some protection to the lender because the asset has a value greater than the loan amount at the time of financing.
LTV and Down Payment
LTV is closely connected to the down payment.
If the lender finances 80% of an asset’s value, the borrower generally needs to arrange the remaining 20%, subject to the applicable financing structure.
For example:
| Asset Value | LTV | Loan | Borrower’s Contribution |
| ₹50 lakh | 70% | ₹35 lakh | ₹15 lakh |
| ₹50 lakh | 80% | ₹40 lakh | ₹10 lakh |
| ₹50 lakh | 90% | ₹45 lakh | ₹5 lakh |
A lower LTV generally means a larger upfront contribution from the borrower.
Higher LTV Means Higher Exposure
From the lender’s perspective, a higher LTV means more of the asset’s value is financed through debt.
For example:
60% LTV: Lower loan exposure relative to asset value
90% LTV: Higher loan exposure relative to asset value
If the asset’s value falls, a high-LTV loan can reach a situation where the outstanding debt is close to or even greater than the recoverable value of the asset.
This is sometimes described as negative equity when the debt exceeds the asset’s value.
LTV Is Not the Same as Loan Eligibility
A common misunderstanding is that an LTV limit tells you exactly how much loan a particular borrower will receive.
It does not.
LTV is only one part of the lending decision.
A lender may also consider:
- Income
- Existing debts
- Credit history
- Repayment capacity
- Employment or business stability
- Asset valuation
- Loan purpose
- Internal lending policies
Therefore, even if an asset supports a particular loan amount under the applicable LTV framework, the borrower may not necessarily qualify for that entire amount.
Asset Valuation Matters
The value used for calculating LTV may not simply be the price written in the purchase agreement.
Depending on the loan and lender, the lender may obtain or rely on a valuation of the asset.
This is particularly important in property lending.
Suppose a seller asks for ₹70 lakh but the lender’s acceptable valuation is ₹60 lakh.
If the lender applies an 80% LTV to ₹60 lakh, the loan supported by that valuation would be:
₹60 lakh × 80% = ₹48 lakh
The borrower may therefore need to arrange a larger amount from their own funds.
The exact treatment depends on the lender and applicable rules.
Why Market Value Can Change
Asset prices are not guaranteed to remain constant.
A property purchased today may be worth more or less several years later.
Similarly, vehicles generally depreciate over time.
This creates different risks for lenders depending on the type of asset.
An asset that loses value quickly can provide less security over time than an asset whose value is relatively stable.
LTV in Home Loans
LTV is particularly important in mortgage lending.
The lender provides financing against the property, while the property serves as security for the loan.
The lender needs to consider what could happen if:
- The borrower stops making payments.
- The lender enforces its security rights according to applicable law.
- The property needs to be sold.
- The property’s recoverable value is lower than expected.
A lower LTV can reduce the lender’s potential exposure.
LTV in Vehicle Loans
LTV can also be relevant to vehicle financing.
Vehicles generally depreciate over time.
A vehicle purchased for ₹10 lakh may be worth considerably less after several years.
If the loan balance remains high while the vehicle’s value falls rapidly, the lender’s collateral cushion can become smaller.
This is one reason vehicle financing structures can differ from property financing.
Why LTV Can Affect Loan Terms
LTV can influence how a lender structures a loan.
Depending on the product and lender’s policies, a higher LTV may be associated with:
- Greater lender risk
- Higher borrower contribution requirements in some cases
- Different pricing
- Additional eligibility conditions
However, LTV does not operate independently.
Creditworthiness and other underwriting factors also matter.
LTV and Interest Rates
It is sometimes assumed that a lower LTV automatically means a lower interest rate.
That is not necessarily true for every loan.
Interest rates are influenced by multiple factors, including:
- Borrower’s credit profile
- Loan type
- Tenure
- Market interest rates
- Lender’s funding costs
- Security
- Lender-specific pricing
LTV can be one factor among many.
What Happens When the Borrower Repays the Loan?
As the borrower makes principal repayments, the outstanding loan balance decreases.
Suppose:
Original asset value: ₹50 lakh
Original loan: ₹40 lakh
Initial LTV:
80%
After several years, suppose the outstanding loan falls to ₹30 lakh.
If the asset’s value remains ₹50 lakh, the loan-to-value ratio becomes:
₹30 lakh ÷ ₹50 lakh × 100 = 60%
The borrower’s equity in the asset has increased, assuming the asset value has remained unchanged.
LTV Can Also Change Because of Asset Prices
The LTV ratio does not change only when the loan balance changes.
If the asset’s market value changes, the relationship between debt and asset value also changes.
For example:
Loan outstanding: ₹40 lakh
If asset value is ₹50 lakh:
LTV = 80%
If asset value falls to ₹45 lakh:
LTV = 88.9%
The borrower has not taken any additional loan, but the LTV has increased because the asset value declined.
Why Borrowers Should Care About LTV
LTV is not just a bank’s internal risk measure.
It also affects borrowers.
A lower LTV generally means the borrower needs to provide more money upfront.
However, having more equity in an asset can also reduce the amount of debt relative to the asset’s value.
A borrower should therefore consider both:
Upfront affordability
and
Long-term debt exposure
LTV vs Down Payment
These concepts are closely related but not identical.
LTV tells you what percentage of the asset’s value is financed through the loan.
Down payment generally refers to the portion paid by the buyer rather than financed through the loan.
For a simplified example:
- Asset value: ₹50 lakh
- LTV: 80%
- Loan: ₹40 lakh
- Borrower’s contribution: ₹10 lakh
Here, the financing portion is 80% and the remaining 20% is contributed by the borrower.
However, actual transaction costs such as registration, taxes, insurance or other charges may require additional funds depending on the transaction.
Final Thoughts
The Loan-to-Value ratio helps lenders measure how much debt is being provided compared with the value of the asset securing that debt.
Banks and other lenders generally avoid financing the entire asset value because asset prices can fall and the amount recovered from selling an asset may be lower than expected.
A lower LTV gives the lender a larger cushion and requires the borrower to contribute more of their own money.
For borrowers, understanding LTV is useful because it explains why a lender may approve a loan for less than the full purchase price.
The key idea is simple:
The more of an asset’s value that is financed through debt, the greater the lender’s exposure if the asset loses value or the borrower defaults.