Sum Insured vs Sum Assured: Why the Terms Are Not Interchangeable
Sum Insured and Sum Assured may sound almost identical, but they are generally used in different types of insurance and can represent different ways of defining the insurer’s financial obligation.
The distinction is especially important when comparing health/general insurance with life insurance.
Although everyday conversations sometimes use the terms interchangeably, they should not be treated as identical when reading insurance documents.
What Is Sum Insured?
Sum Insured generally refers to the maximum amount an insurer is liable to pay under an insurance policy for covered losses, subject to the policy’s terms, limits, exclusions and other conditions.
It is commonly associated with health insurance and general insurance products.
For example, suppose a health insurance policy has a sum insured of ₹10 lakh.
This does not necessarily mean the policyholder will receive ₹10 lakh.
It generally represents the maximum coverage available for eligible claims during the applicable policy period, subject to the policy conditions.
What Is Sum Assured?
Sum Assured is commonly used in life insurance to describe the amount specified as the insurance benefit under the policy, subject to its terms and conditions.
For example, a life insurance policy may have a sum assured of ₹1 crore.
If the insured event covered by the policy occurs, the applicable benefit may be calculated with reference to the sum assured and the policy’s terms.
The exact benefit payable can depend on the type of life insurance product.
The Basic Difference
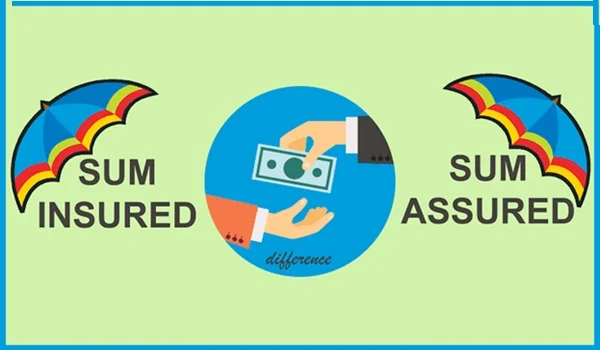
A simple way to remember the distinction is:
Sum Insured → Commonly used for health and general insurance
Sum Assured → Commonly used for life insurance
However, terminology can vary between products and policy documents, so the actual policy wording should always take priority over assumptions based solely on the term.
Sum Insured in Health Insurance
Suppose you have a health insurance policy with a ₹10 lakh sum insured.
During the policy period, you incur eligible hospitalization expenses of ₹3 lakh.
Subject to the policy’s terms, the insurer may pay the eligible claim up to ₹3 lakh rather than automatically paying the full ₹10 lakh.
The remaining available coverage may depend on the policy structure and whether other claims have already been made.
Therefore, the sum insured represents the available coverage limit, not a guaranteed payout.
Sum Assured in Life Insurance
Now consider a term life insurance policy with a ₹1 crore sum assured.
If the insured event occurs while the policy is active and all applicable conditions are satisfied, the death benefit is generally determined according to the policy terms and may be linked to the sum assured.
Unlike a health insurance claim, the benefit is not normally based on the amount of a hospital bill.
This reflects a fundamental difference between the two types of insurance.
Why the Terms Exist in Different Contexts
Health and general insurance are generally designed to provide financial protection against specified losses or expenses.
Life insurance, particularly protection-oriented life insurance, provides a predefined benefit upon an insured event such as death, according to the policy terms.
Therefore:
Health insurance → Financial protection against eligible healthcare expenses
Life insurance → Financial benefit upon the occurrence of the insured event
This is one reason different terminology is commonly used.
Sum Insured vs Sum Assured
| Factor | Sum Insured | Sum Assured |
| Commonly associated with | Health/general insurance | Life insurance |
| Basic concept | Coverage limit for insured losses | Specified insurance benefit |
| Common example | ₹10 lakh health cover | ₹1 crore life cover |
| Claim calculation | Often linked to eligible loss/expenses | Generally specified by policy terms |
| Full amount automatically paid? | No | Not necessarily; depends on policy terms |
| Main purpose | Cover specified financial losses | Provide predetermined insurance benefit |
Sum Insured Does Not Mean Every Expense Is Covered
A ₹10 lakh sum insured does not mean that every ₹10 lakh of medical expenses will necessarily be paid.
The claim remains subject to:
- Covered treatments
- Exclusions
- Waiting periods
- Deductibles
- Co-payments
- Sub-limits
- Policy conditions
- Applicable claim rules
For example, if a policy has a ₹10 lakh sum insured but a particular treatment is excluded, that treatment may not be covered simply because sufficient sum insured remains available.
Sum Assured Does Not Mean Every Life Insurance Policy Pays Exactly That Amount
The actual benefit depends on the policy structure.
Different life insurance products can have different benefit calculations.
For example, a policy may include:
- Death benefit
- Maturity benefit
- Bonuses
- Riders
- Guaranteed benefits
- Other contractual benefits
Therefore, customers should not assume that the phrase “sum assured” by itself explains every possible payout.
The policy schedule and benefit illustration provide the relevant details.
What Happens When Multiple Health Claims Are Made?
Consider a health insurance policy with a ₹10 lakh annual sum insured.
Suppose the policyholder makes an eligible claim of ₹4 lakh.
If another eligible claim of ₹3 lakh occurs during the same policy period, the available coverage may be reduced accordingly, subject to the policy’s terms.
This illustrates why the sum insured in health insurance functions differently from a fixed life insurance benefit.
Can Sum Insured Be Restored?
Some health insurance policies offer features such as restoration or refill of the sum insured.
For example, after the original coverage is exhausted, the policy may restore some or all of the coverage under specified conditions.
However, restoration is not automatic across all policies.
The customer must check:
- When restoration applies
- Whether it applies to the same illness
- Whether it can be used more than once
- Whether it applies to individual or family claims
- Other applicable conditions
Can Sum Assured Change?
In life insurance, the sum assured can vary depending on the product.
For example, certain policies may have:
- Increasing benefits
- Decreasing benefits
- Multiple benefit structures
- Riders providing additional coverage
Therefore, the policy document remains more important than simply looking at the headline sum assured.
Why Confusing the Terms Can Cause Problems
Using the terms interchangeably can lead to incorrect expectations.
For example, someone may think:
“My health insurance has a ₹10 lakh sum insured, so I will receive ₹10 lakh if I make a claim.”
That is generally incorrect.
Similarly, someone may misunderstand a life insurance policy by treating the sum assured as if it were a reimbursement limit for expenses.
The two concepts operate differently.
Sum Insured and Sum Assured Are Not the Same as Premium
Another common confusion is between coverage and premium.
Premium = Amount paid to maintain the insurance policy.
Sum Insured = Coverage limit commonly used in health/general insurance.
Sum Assured = Specified insurance benefit commonly used in life insurance.
For example:
- Health insurance premium: ₹20,000 per year
- Health insurance sum insured: ₹10 lakh
- Life insurance premium: ₹15,000 per year
- Life insurance sum assured: ₹1 crore
These numbers represent completely different things.
Why Policy Wording Matters
Insurance terminology can vary across products and jurisdictions.
Therefore, customers should not rely solely on a general definition found online.
The policy schedule, policy wording, benefit illustration and applicable regulatory requirements should be used to determine exactly what a particular insurer means by a term and how the benefit will be calculated.
This is particularly important when policies contain special conditions, riders or multiple benefit components.
Final Thoughts
Sum insured and sum assured may sound similar, but they generally serve different purposes.
Sum insured is commonly associated with health and general insurance and represents the coverage available for eligible losses, subject to policy conditions. Sum assured is commonly associated with life insurance and refers to the specified insurance benefit under the policy.
The distinction matters because the amount shown on an insurance document does not automatically tell you what you will receive in every situation.
Before purchasing or comparing insurance, look beyond the headline figure and check the coverage limits, exclusions, deductibles, waiting periods, benefit structure and claim conditions.
In short, ₹10 lakh sum insured and ₹10 lakh sum assured should not automatically be treated as equivalent forms of insurance protection.